Business valuation is a central building block of every business succession, every transaction and many strategic decisions. Anyone who wants to buy, sell or hand over a company in Switzerland will sooner or later ask the same question: how much is the company actually worth?
This is exactly where uncertainty often begins in practice. Many entrepreneurs are guided by personal expectations, rough market comparisons or individual key figures. Buyers, in turn, want to understand whether an asking price is plausible and how the company value can be derived methodically. A well-founded business valuation creates an objective basis for this.
Business Successor supports buyers and sellers in assessing company values realistically and making valuation logic understandable. You will find the complete overview of business succession in Switzerland on our main page.
Why business valuation is so important
Valuing a company is far more than an arithmetical exercise. It forms the basis for central decisions in the succession and purchase process. A realistically determined value provides orientation, reduces misunderstandings and improves the negotiating basis between the parties.
For sellers, business valuation is important in order to go to market with a plausible price expectation. For buyers, it is decisive in order to assess opportunities and risks correctly and make a well-founded purchase decision. At the same time, a company value is never simply a fixed number, but arises from a combination of method, assumptions, expectations for the future and the specific situation of the buyer.
What is actually valued in a business valuation?
Business valuation is not only about existing assets. What is valued is first and foremost the economic substance and future viability of a company. Typical influencing factors are:
- Revenue and earning power
- Stability of profits
- Assets and equity
- Dependence on individual customers or key people
- Market position and competitiveness
- Future prospects and investment requirement
- Quality of processes and organisation
With Swiss SMEs in particular, the personal imprint of the owner often plays an additional role. If the company is heavily dependent on the owner, this often affects the value considerably.
The most important valuation methods in Switzerland
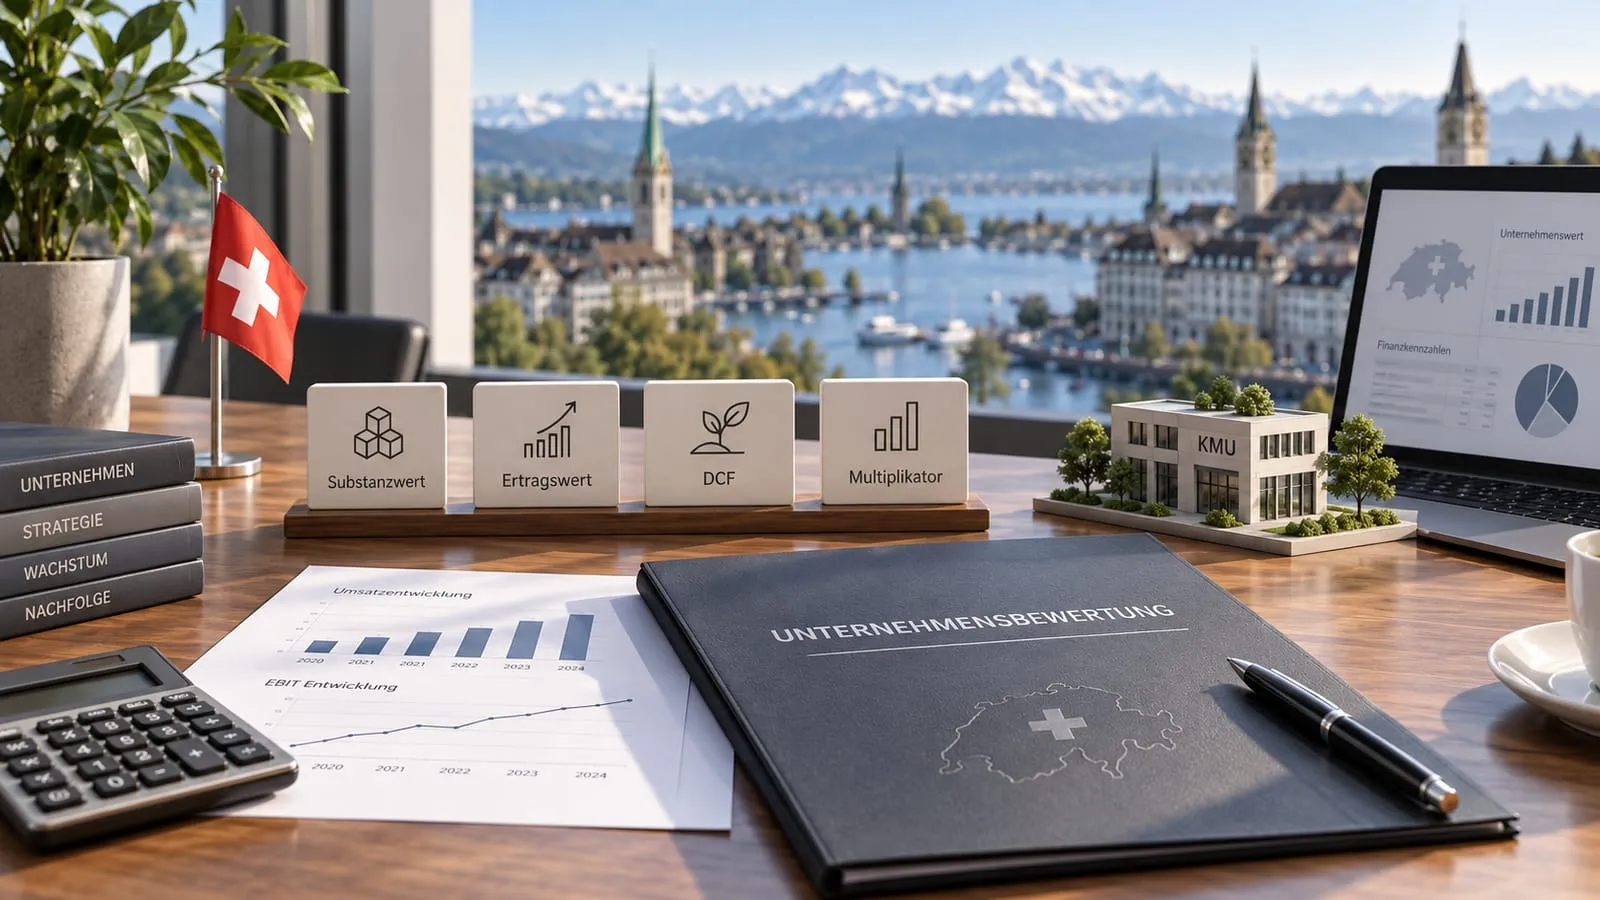
In practice, there is no single right method for every situation. Depending on the company, industry and objective, different approaches are used. The most important methods can be divided into three main categories.
Net asset value method
The net asset value method looks at the value of the company’s individual assets, that is, cash and cash equivalents, receivables, machinery, vehicles, real estate and inventories. Liabilities are deducted from these values and hidden reserves are added. The result is the net asset value.
The net asset value is particularly important where tangible assets play a major role, for example in production-related businesses or real estate-related companies. It is relatively easy to follow and shows the material basis of the company. The decisive disadvantage, however, is that future earning power is only insufficiently taken into account. It therefore serves well as a lower limit for other valuation methods.
Earnings value method
The earnings value method is one of the most important methods in SME valuation. Here the focus is not on the past, but on the question: what future earnings can the company generate sustainably?
The expected future profits or cash flows are converted to their present-day value. The higher and more stable the expected earnings, the higher the company value. For many buyers, this is the central point: they buy a company because of its future economic performance, not because of furniture or machinery. However, the method depends heavily on assumptions, and small changes can lead to markedly different results.
Discounted cash flow (DCF)
The DCF method is a further development of the earnings value concept. Instead of working with simplified profit figures, future free cash flows are estimated and discounted to their present value. It is particularly widespread in the M&A environment and theoretically very sound. For many smaller SMEs without a formalised financial plan, however, it is too complex as a first step and more of an instrument for in-depth analysis than a simple entry-level approach.
Multiples method
With the multiples method, the company value is derived on the basis of comparative values. Typical reference figures are revenue, EBITDA, EBIT or profit. If comparable companies in an industry are typically sold at a factor of 4 to 6 times EBITDA, this multiple is applied to the company being valued.
The method is easy to understand, practical and widespread in SME sales. The big catch, however, lies in comparability: no two companies are exactly alike, and differences in customer structure, dependencies, growth or region can in reality limit the validity of a seemingly suitable multiple.
Which method is the right one?
In practice, business valuation in Switzerland is often not based on a single method. Rather, a combined view makes sense: net asset value for the material basis, earnings value or DCF for the economic future, multiples for the market logic. With SMEs in particular, this combined approach usually leads to the most robust results.
Which method is used most often in practice
In business valuation, various methods such as the net asset value, earnings value, DCF and multiples methods are available, and their suitability and informative value differ depending on the purpose of the valuation, the company and the available data. In Swiss practice, one picture emerges above all: in SME transactions, fiduciaries predominantly work with a combination of earnings value and net asset value.
The so-called practitioner method is widespread; it combines earnings value and net asset value on a weighted basis, frequently in a ratio of two to one in favour of the earnings value. It originally comes from tax practice and is therefore familiar to many of those involved. Its advantage lies in its transparency: buyer, seller, bank and tax authority can follow the same calculation without arguing about planning assumptions.
The reason for this pragmatic approach lies in the structure of small companies. Many Swiss SMEs have no formalised financial plan covering several years, their results fluctuate, and the owner’s salary distorts the figures. In this starting position, an elaborate model does not deliver a better answer, only one that looks more precise. What matters is therefore less the method than the clean adjustment of the figures: normalising the owner’s salary to market level, stripping out private expenses, adjusting for one-off effects and taking the investment requirement into account. In technical jargon, this process is referred to as the reconciliation from reported to normalised EBITDA.
DCF or multiples: what really suits SMEs
Both methods answer the same question from two directions, and they are suited to different situations.
The DCF method derives the value from the future free cash flows, which are discounted to the present day. It makes sense where robust planning over three to five years exists, for example in rather larger SMEs, with predictable recurring revenues or when a specific investment will foreseeably change earnings. Its limit lies in planning uncertainty: for a business with ten employees and fluctuating orders, the result depends almost entirely on the assumptions chosen. Small changes in the discount rate or in long-term growth shift the value by hundreds of thousands. A DCF value without a sensitivity analysis says little in the case of an SME.
The multiples method starts from the market. An adjusted EBITDA is multiplied by a factor customary in the industry. For Swiss SMEs, these factors frequently range between four and seven depending on industry, size and quality of earnings, lower for very small or heavily owner-dependent businesses, higher for scalable business models. The advantage is the closeness to the market and the fact that it is quickly understood; the disadvantage lies in comparability, because the multiple of another company reflects its customer structure and dependencies, not yours. In addition, the necessary differentiation within individual industries can often only be inadequately reflected with publicly available data.
In valuation practice, a mix of methods with multiples and earnings value is usually calculated for SMEs, and DCF is used as a supplement where planning is available. It is important that the methods lead to similar orders of magnitude. If they diverge sharply, this is not a calculation error but an indication of a risk in the company that should be followed up in the due diligence.
What does a business valuation cost?
A professional valuation for a Swiss SME costs between CHF 1’000 and 8’000 depending on the scope. A compact estimate based on the annual financial statements lies at the lower end, a detailed valuation with adjustments, scenarios and a written report at the upper end. For complex structures with several companies, real estate or international activities, the effort can be higher.
The costs depend above all on three factors: the quality of the available documents, the complexity of the structure and industry, and the purpose of the valuation. A valuation for initial orientation is cheaper than one that has to stand up before banks, tax authorities or in a negotiation.
Typical mistakes in business valuation
- Being guided too strongly by wishful thinking: Sellers sometimes equate the value with their personal life’s work. This is emotionally understandable, but does not lead to a marketable valuation.
- Looking at only one key figure: A single revenue figure or an EBITDA multiple is rarely enough. The overall logic is decisive.
- Misjudging the future and the risks: High results in the past do not automatically mean stable future earnings.
- Underestimating dependence on the owner: If customer relationships or specialist knowledge depend heavily on one person, this has a direct effect on the value.
- Ignoring market logic: Theoretical values and the market prices that can actually be achieved are not always identical.
Initial estimate with the company valuation calculator
Before you commission a valuation, it is worth getting a first order of magnitude. Our company valuation calculator provides a guide value based on a few key figures and shows the range within which a purchase price is likely to fall. It helps you to understand initial orders of magnitude and to prepare better for discussions about price and value.
However, it does not replace a well-founded examination of the individual case, because qualitative factors such as dependencies, readiness for succession or operational risks can only be reflected in a standardised way to a limited extent. For the negotiation or the financing, a well-founded examination of the individual case is then needed, for example as part of the business acquisition.
Conclusion: business valuation in Switzerland creates clarity
Whether business succession, sale or purchase, a well-founded business valuation creates transparency and improves the basis for decision-making. The most important methods, net asset value, earnings value, DCF and the multiples method, help you to take different perspectives on a company. In many situations, a combined view is the best way.
Business Successor supports buyers and advisers in assessing company values realistically and preparing succession processes professionally. If you would like to obtain a first guide value, use our company valuation calculator. For more in-depth support, you will find the starting point on our page on business succession in Switzerland or directly in a no-obligation initial consultation.