Many experienced executives face one question in the course of their career: should I keep working for others or run a company of my own? The classic career path often leads to ever more senior salaried roles. But if you want to think and act as an entrepreneur without starting from zero, a management buy-in is an attractive route.
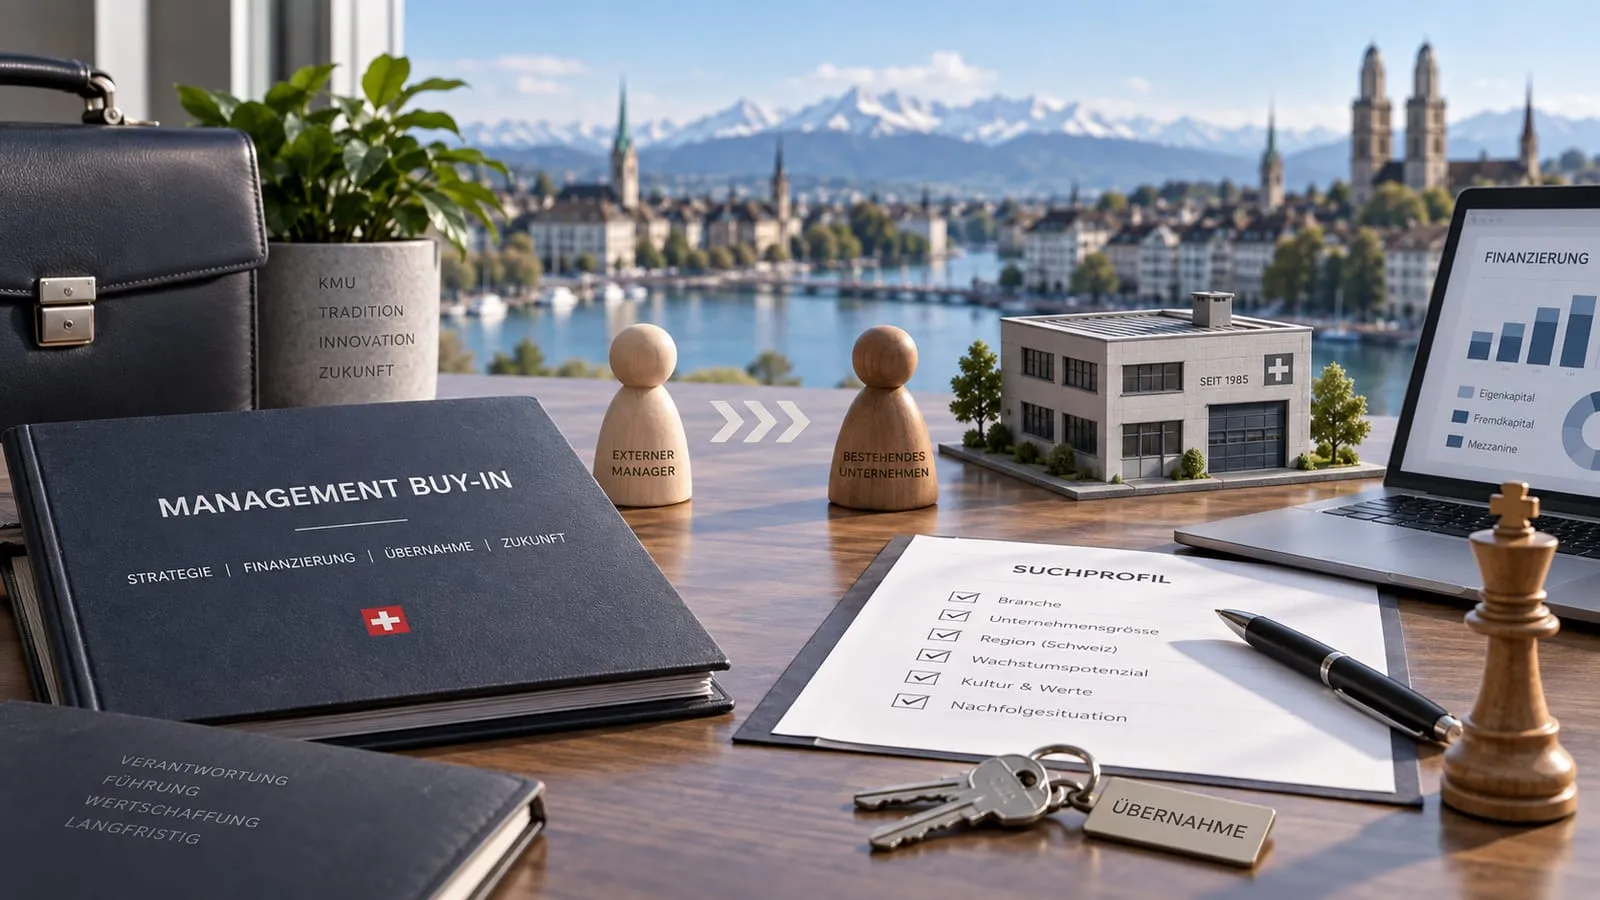
A management buy-in (MBI) means that an external executive acquires an existing company and, as its new owner, takes on operational responsibility. In contrast to a management buy-out, where the internal management team takes over, the buyer comes from outside. The model is particularly relevant in the Swiss SME market because many entrepreneurs cannot find a successor internally or within the family and look for an external leader instead.
Business Successor supports MBI candidates along this path: from strategic clarification and the search for a company through to the transaction. You will find the full framework on business succession in Switzerland on our main page.
What exactly does management buy-in mean?
A management buy-in is the purchase of an existing company by an external executive who then takes over the operational management personally. The buyer generally brings three things:
- Management experience: operational leadership skills, an understanding of the industry and entrepreneurial thinking
- Capital or financing: own funds, debt capital or investors
- The will to shape things: the desire to run and develop a company as its owner
That distinguishes an MBI from a pure investment. Anyone who takes over a company by way of a management buy-in invests not only money but also themselves as the operational leader. That is exactly what makes the model so attractive to many managers: they can carry their experience from a salaried role over into entrepreneurial responsibility of their own.
Who is a management buy-in suitable for?
Not every executive is automatically an MBI candidate. The model is particularly suitable for people who bring a combination of operational experience, entrepreneurial thinking and a willingness to commit capital.
Experienced executives
Typical MBI candidates have already held operational leadership responsibility. They understand how companies work, how teams are led and how economic relationships play out in practice. This experience is crucial, because in a management buy-in they do not just acquire a company, they also run it themselves straight away.
Entrepreneurially minded personalities
An MBI is not just a career step, it is an entrepreneurial step. Anyone who chooses this path must be able to make decisions, bear risk and want to take on entrepreneurial responsibility. The model is therefore less suitable for people who prefer security and clear instructions, and more for those who want to shape things.
Subject and industry experts
Ideal candidates have in-depth knowledge of an industry. That may be a specialist who takes over a company in the same industry, or an executive who works well across industries and quickly gets to grips with new markets.
People willing to commit capital, with or without investors
An MBI generally requires a certain contribution of your own. Many candidates, however, do not finance the purchase alone but with investors, banks or in search fund structures. That, too, is a legitimate route, as long as operational management lies with the buyer.
Why buy a company instead of founding one?
For many MBI candidates, the central decision is: buy a company instead of founding one. Both routes lead to self-employment, but they differ considerably.
Anyone who founds a company starts from zero. There are no customers, no employees, no processes and no revenue. Everything has to be built from scratch. That is creative, but also risky, time-consuming and often associated with considerable uncertainty.
Anyone who takes over a company by way of a management buy-in, by contrast, starts on an existing basis: customers and revenue are already there, employees and know-how exist, processes and infrastructure are established, market position and networks have often been built up, and permits and legal foundations are in place.
That reduces the risk, shortens the path to operational responsibility and makes it possible to build on a solid economic foundation from the outset. Particularly for experienced managers who no longer want to start from zero, that is a decisive advantage.
The Swiss market for management buy-ins
Switzerland offers an attractive environment for management buy-ins. The SME market is broad, stable and specialised in many industries. At the same time, numerous companies will be facing succession planning in the coming years. Many owners cannot find a suitable solution within the family or the existing management team and look for an external leader instead.
That creates concrete opportunities for MBI candidates. The prerequisite, however, is that they understand the market, search actively and do not wait for a suitable opportunity to turn up by itself. Good acquisition targets are rarely advertised publicly; they often arise discreetly through networks, advisers or specialised platforms.
The first steps towards a management buy-in
Anyone planning an MBI in Switzerland should proceed in a structured way. The following steps help to clarify the process early on and create the conditions for a successful takeover.
Step 1: Clarify your own role and objectives
It starts with the question of your own role. Do I want to lead operationally? In which industry? What size of company suits me? What responsibility do I want to take on? And what financing is realistic? Candidates who answer these questions honestly avoid expensive wrong decisions later on.
Step 2: Define the search profile
The search profile follows from your own role. Typical criteria are industry, company size, region, earnings situation, number of employees or investment requirements. If you define a precise profile, you find suitable opportunities faster and waste no time on unsuitable companies.
Step 3: Prepare the financing
An MBI requires sound financing logic. Own funds, bank loans, investors, search funds or hybrid forms are all possible. You will find more on financing a management buy-in further down in the section “How is a management buy-in financed?”.
Step 4: Identify companies
Good MBI target companies rarely come about by chance. Successful candidates search actively through networks, advisers, platforms and direct outreach. Business Successor helps to identify suitable companies in the Swiss SME market and to build access to discreet opportunities.
Step 5: Initial assessment and due diligence
As soon as a suitable company has been identified, a well-founded review is needed. This includes the financial, legal, tax and operational analysis. In an MBI in particular, due diligence in a business acquisition is crucial, because the buyer will later be operationally responsible for what is being reviewed now.
Step 6: Negotiation and structuring
The negotiation covers not only the purchase price but also the transaction structure, the transition arrangements, warranties and the shape of the first phase after the takeover. A sound purchase agreement protects the buyer side and creates clarity about the framework for the coming months and years.
Step 7: Transition and integration
Operational responsibility begins after the purchase agreement. The first months are decisive: building trust among employees, stabilising customer relationships, understanding processes and establishing your own leadership role. If you actively shape the transition phase, you lay the foundation for successfully developing the company further.
Typical challenges in an MBI
Anyone who takes over a company by way of a management buy-in faces not only an opportunity but also concrete challenges.
Recognising owner dependency
Many Swiss SMEs are closely tied to the person of the previous owner. Customer relationships, knowledge and operational control often depend on individuals. A careful analysis of these dependencies is therefore central, ideally as part of due diligence.
Building trust within the team
An external purchase sometimes leads to uncertainty within the team. Employees wonder what will change, whether their job is safe and what makes the new leader tick. Transparent communication and a clear stance in the first weeks are decisive.
Stabilising customer relationships
Existing customers should stay after the change of ownership too. If you seek contact early, convey stability and make continuity visible, you protect the company’s most important foundation.
Assessing the financial reality
Not every attractive company is also a good MBI target. Sometimes the purchase price is too high, the earnings too volatile or the investment requirement too large. A realistic business valuation in Switzerland protects against wrong decisions.
How is a management buy-in financed?
Financing is the point in a management buy-in where most candidates get stuck the longest. The reason lies in the starting position: in an MBI, the buyer side comes from outside. It does not know the company from the inside, has no history with customers and employees and first has to demonstrate to banks and investors that it can run the business.
As a guideline, 20 to 30 per cent equity is needed, relative to the purchase price. With stable earnings and good collateral it can be less; with fluctuating results or high investment requirements, considerably more. If you know this framework, you also know the order of magnitude in which you can search.
Swiss banks assess an MBI differently from an ordinary company purchase. Alongside historical earning power and the affordability of interest and repayments out of ongoing business, the focus is on the person of the buyer: leadership experience, closeness to the industry, business plan and the question of how the company works without the previous owner. Banks generally examine MBI cases more closely than a management buy-out, because in an MBO the team taking over already knows the business. The MBI buyer side has to make up for this knowledge gap through preparation.
Besides the bank, other capital providers come into consideration. Private investors, private equity firms and search fund structures participate in the search and the purchase, but in return demand a say, reporting and orderly governance. A frequent and often underestimated element is the seller loan (vendor loan): the seller defers part of the purchase price. That lowers the capital requirement at closing, bridges differences in price expectations and signals to banks that the seller believes in the company’s future. In an MBI in particular, that is a strong argument towards the financing bank.
You will find an in-depth overview of all the financing building blocks in a business acquisition in the article Buying a business in Switzerland.
Management buy-in compared with management buy-out
Both models lead to the takeover of an existing company, but differ fundamentally in one respect: in a management buy-in an external executive takes over, in a management buy-out the existing internal team does.
From the buyer’s perspective, the MBI brings a fresh view from outside, new methods and often more capital or access to investors. The price for that is a lack of internal knowledge: customer relationships, informal procedures and team dynamics first have to be explored. The MBO turns that around. The team knows the business, customers and risks in detail, but often has less equity and tends to perpetuate what exists rather than question it.
In practice, the MBO is the better fit when a capable second management level is in place and continuity is the priority. The MBI is the right route when nobody internally can or wants to take over, the company has development potential and an external leader brings fresh impetus. Not infrequently a hybrid form also emerges, in which an external person takes over together with parts of the existing management.
Frequently asked questions about management buy-ins
What is the difference between an MBI and an MBO?
In a management buy-in an external executive takes over the company; in a management buy-out it is the management team already working in the company. The essential difference lies in internal knowledge and in capital resources.
How much equity does an MBI require?
As a guideline, 20 to 30 per cent of the purchase price is realistic. The exact share depends on the stability of earnings, the collateral and the seller’s willingness to defer part of the purchase price.
Is an MBI possible without industry experience?
Yes, but it is more demanding. Without industry experience, banks and sellers expect all the more leadership experience, a robust business plan and usually a longer induction by the previous owner.
How long does a typical MBI process take?
From the search profile to closing, you should expect six to twelve months. The search for a suitable company usually takes up the largest part of that time.
What role does the seller play after the takeover?
In an MBI, the seller often stays on board for a transition phase to hand over customers, suppliers and knowledge. Duration, role and remuneration should be set out in the purchase agreement, not agreed verbally.
Conclusion: Management buy-in in Switzerland as a route into entrepreneurship
For executives, the management buy-in is one of the most attractive routes into entrepreneurship. If you take over an existing company instead of founding a new one, you start on a solid basis and can turn your own management experience directly into operational responsibility.
The prerequisite is a clear approach: define the role, build the search profile, clarify the financing early, have the due diligence carried out properly and actively shape the transition phase. If you implement these points consistently, you considerably increase the likelihood of a successful takeover.
Business Successor supports MBI candidates along this path, from clarifying objectives and actively searching for a company through to the professional execution of the transaction. You will find more on the overall topic on our page on business succession in Switzerland, or arrange a no-obligation initial consultation directly.